


I'm renewing my car insurance and the agent asked whether I want a $500 or $1,000 deductible. The $1,000 option saves some money each year, but I'm not sure that's smart if I have an accident. How do I decide which deductible makes sense for me?
Car insurance deductible: should I pick $500 or $1,000?
Concerns & risks
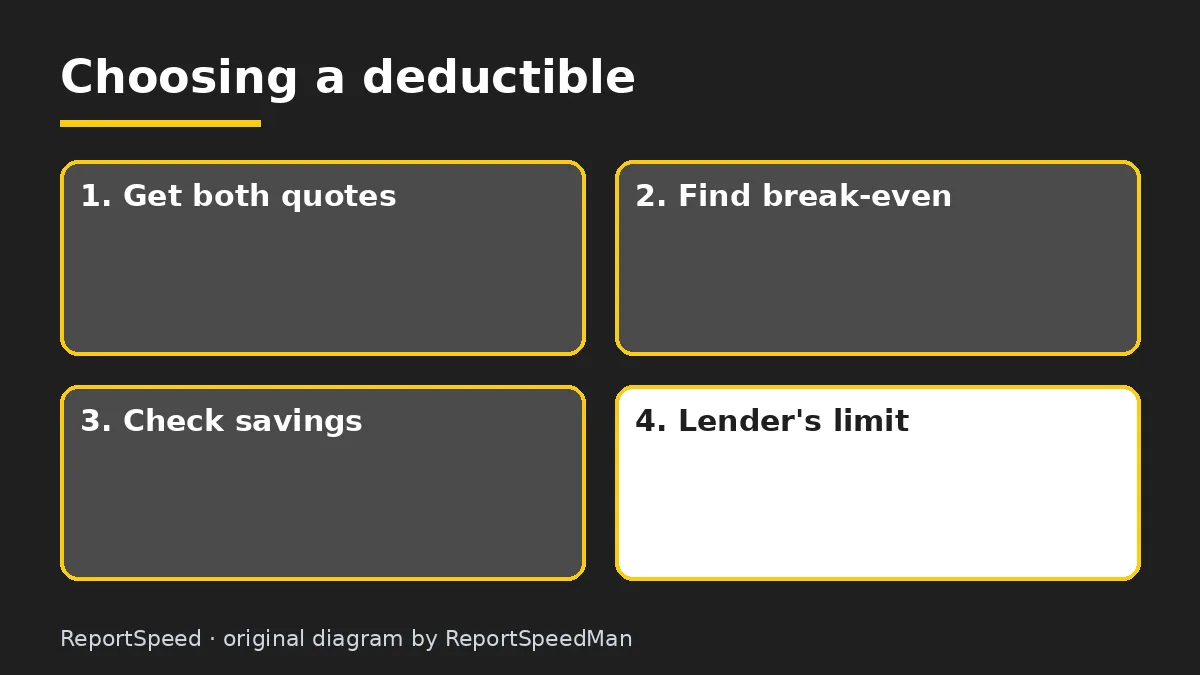
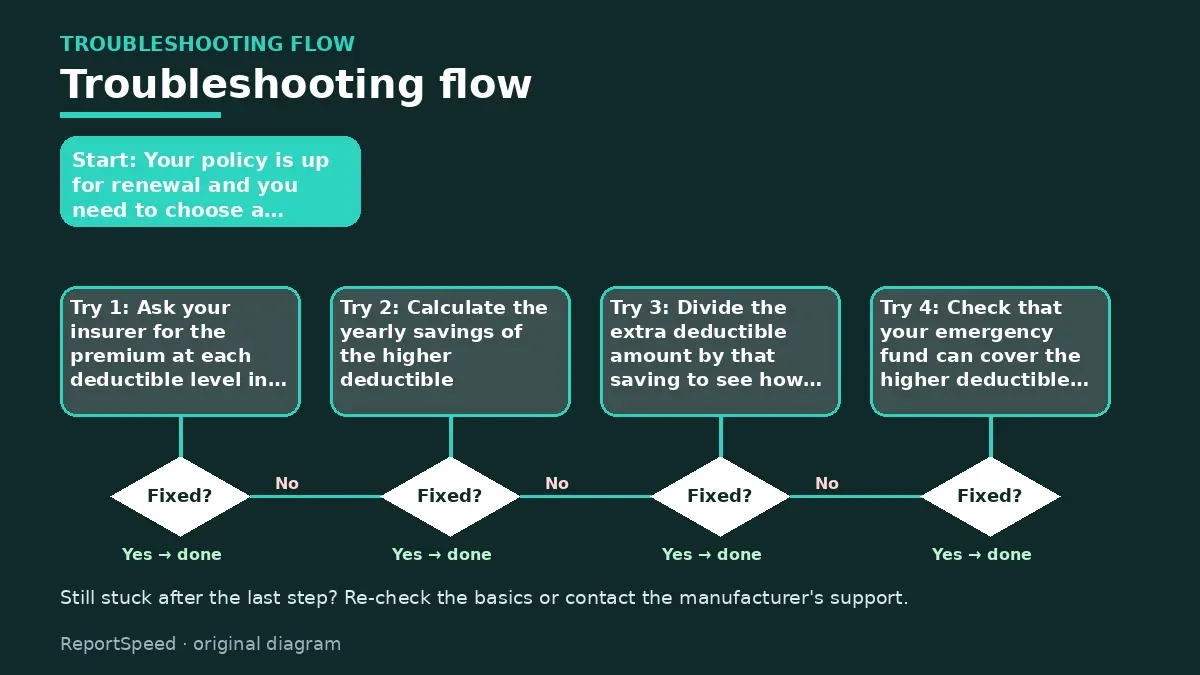
Your policy is up for renewal and you need to choose a deductible without really knowing how it affects you.
| Situation | Often fits |
|---|---|
| Solid emergency fund, few claims | $1,000 |
| Thin savings | $500 |
| Financed car | Within lender's limit |
| Older car of low value | Weigh dropping collision |
Causes & evidence
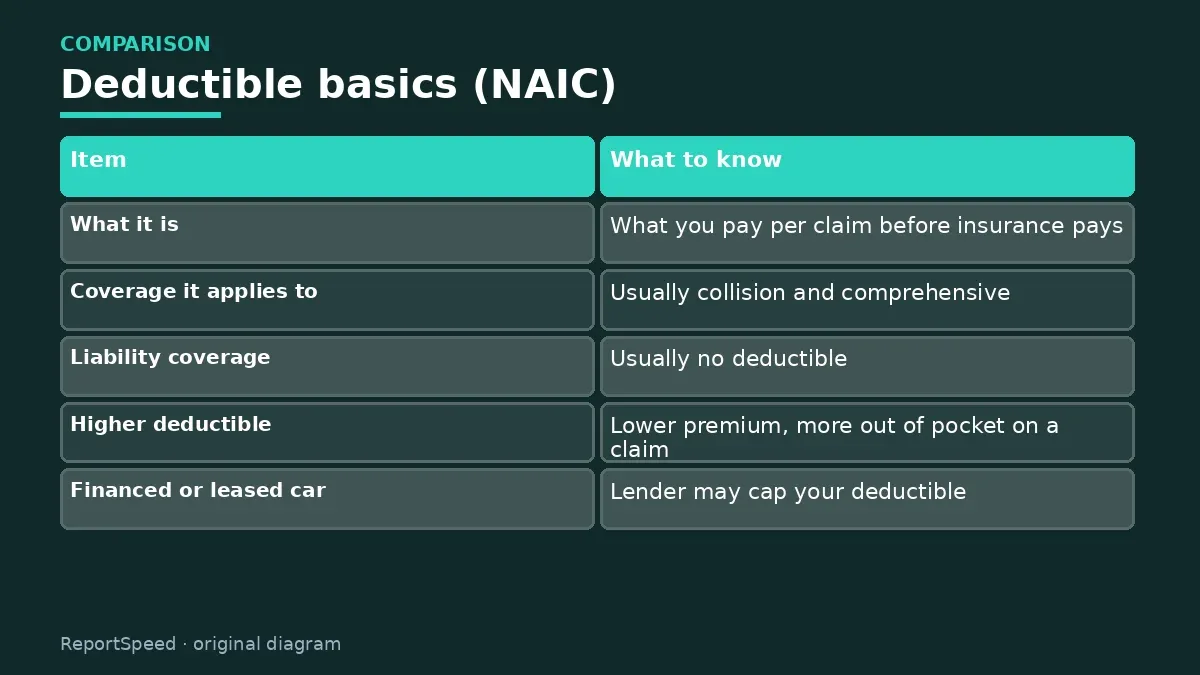
A deductible is the amount you pay out of pocket on a claim before insurance pays the rest. It usually applies to collision and comprehensive coverage, which pay for damage to your own car, and is generally charged per claim. Liability coverage, which pays for damage you cause to others, usually has no deductible. The National Association of Insurance Commissioners explains that choosing a higher deductible generally lowers your premium, while a lower deductible raises it. If your car is financed or leased, the lender may set a maximum deductible you're allowed to choose.
Premiums depend on many factors besides the deductible, including your driving record, location and the car itself. Shop around at renewal.
Picking a $1,000 deductible to save money when you couldn't actually pay $1,000 tomorrow can leave a damaged car unrepaired.
What to do
| Item | What to know |
|---|---|
| What it is | What you pay per claim before insurance pays |
| Coverage it applies to | Usually collision and comprehensive |
| Liability coverage | Usually no deductible |
| Higher deductible | Lower premium, more out of pocket on a claim |
| Financed or leased car | Lender may cap your deductible |
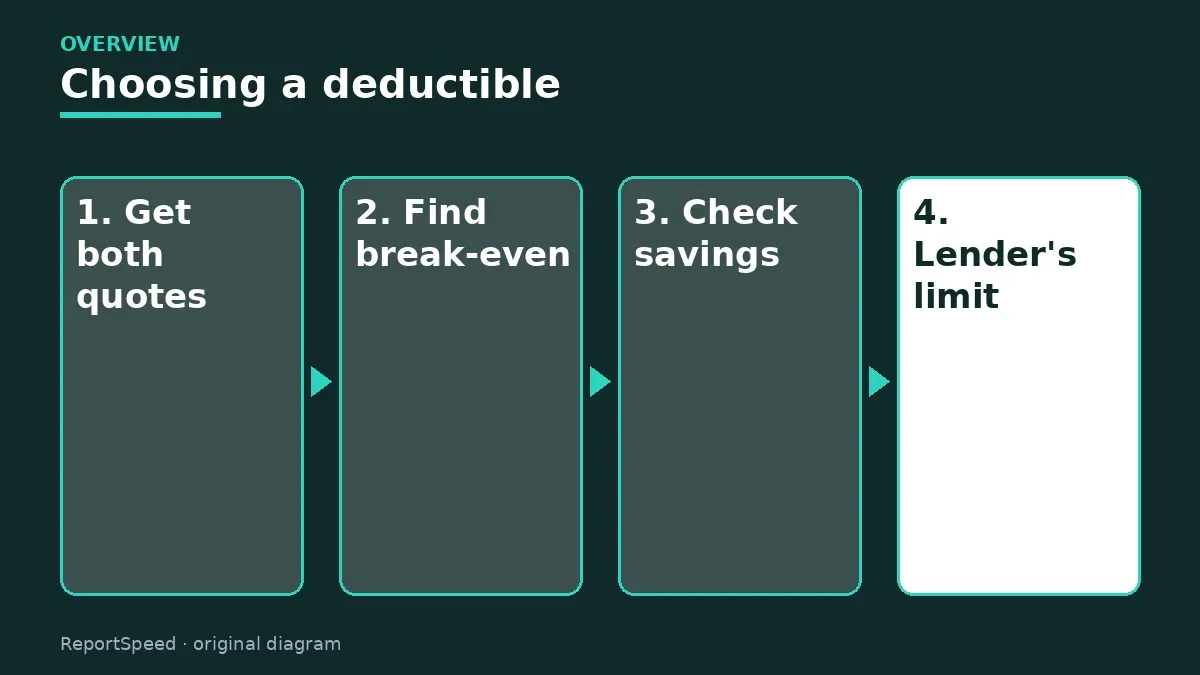
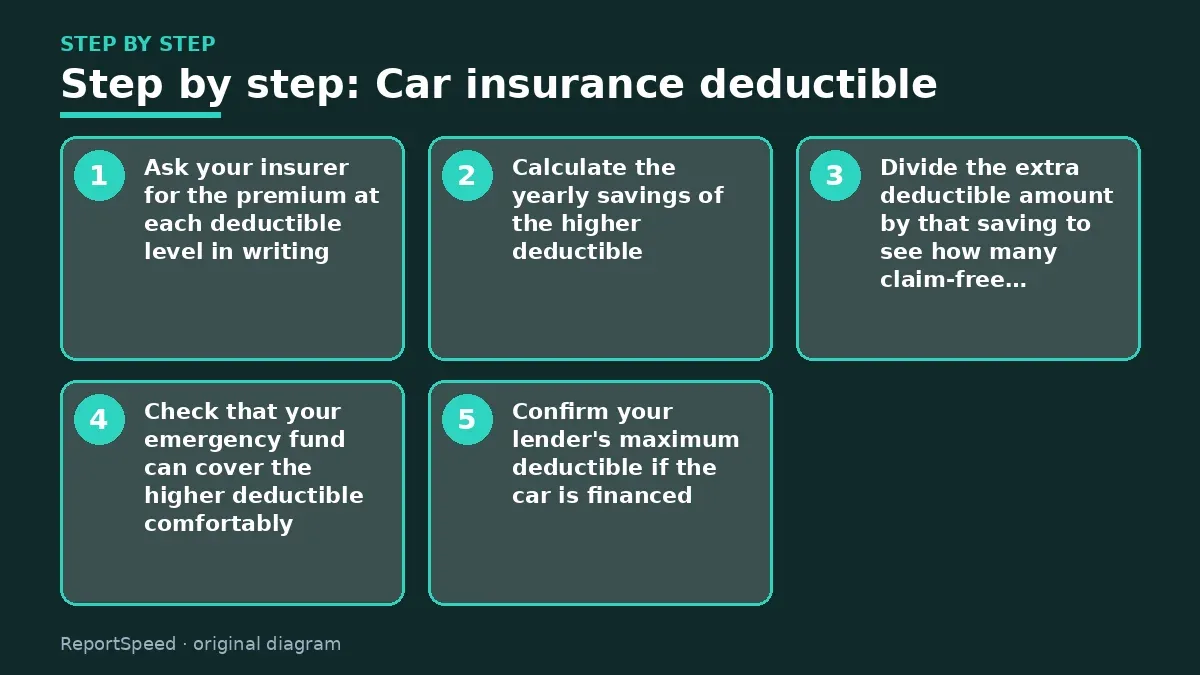
- Ask your insurer for the premium at each deductible level in writing.
- Calculate the yearly savings of the higher deductible.
- Divide the extra deductible amount by that saving to see how many claim-free years it takes to break even.
- Check that your emergency fund can cover the higher deductible comfortably.
- Confirm your lender's maximum deductible if the car is financed.
Common mistakes:
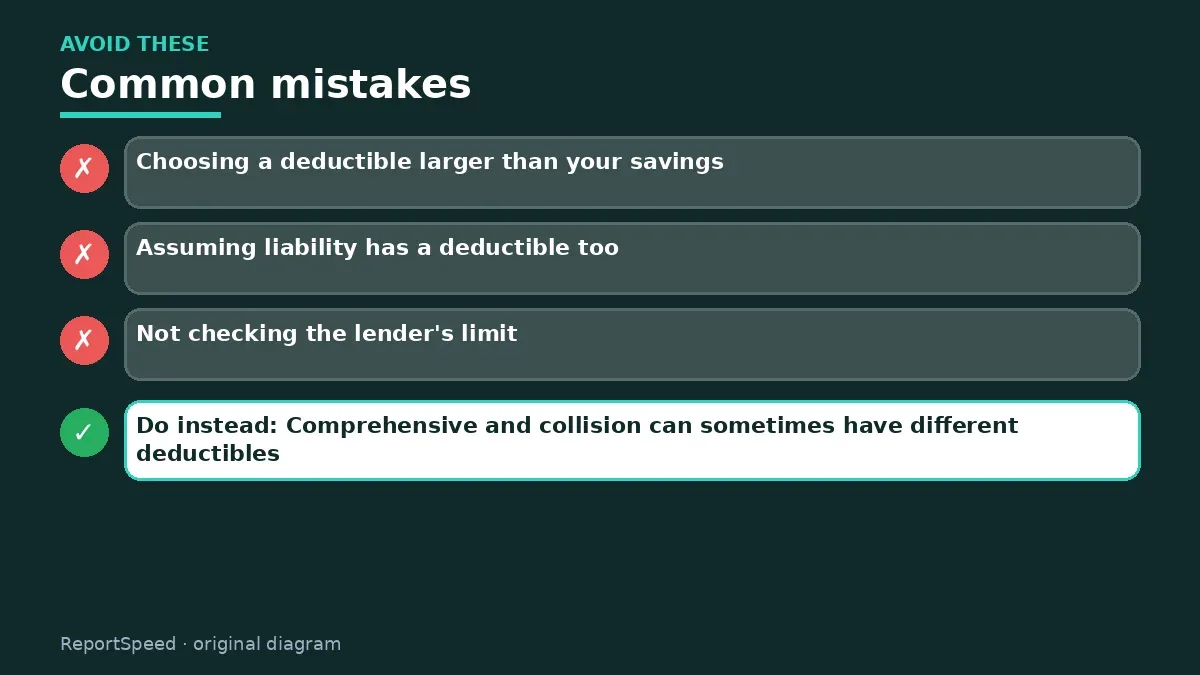
- Choosing a deductible larger than your savings
- Assuming liability has a deductible too
- Not checking the lender's limit
ReportSpeedMan tip: Comprehensive and collision can sometimes have different deductibles. A lower comprehensive deductible may cost little and helps with glass, theft or storm damage.
What I would actually do
if my emergency fund could easily cover $1,000, I'd choose the higher deductible and put the premium savings toward that fund.
The trade-off people miss: with a high deductible, small dents become out-of-pocket repairs, and with a low one, small claims can raise your future premiums anyway.
Proof that it worked
Your deductible is one you could pay tomorrow and your premium is lower.
Quick FAQ
Does liability have a deductible?
Usually no.
Can I change my deductible mid-policy?
Often yes; ask your insurer.
Is comprehensive deductible separate?
It can be.
Wrap-up: Pick the highest deductible you can pay without stress. If your savings are thin, the lower deductible is worth the small extra premium.
Wiki: Emergency Fund and Vehicle Recalls.
Car insurance deductible: read the originals
Step-by-step photos
1. Before The problem 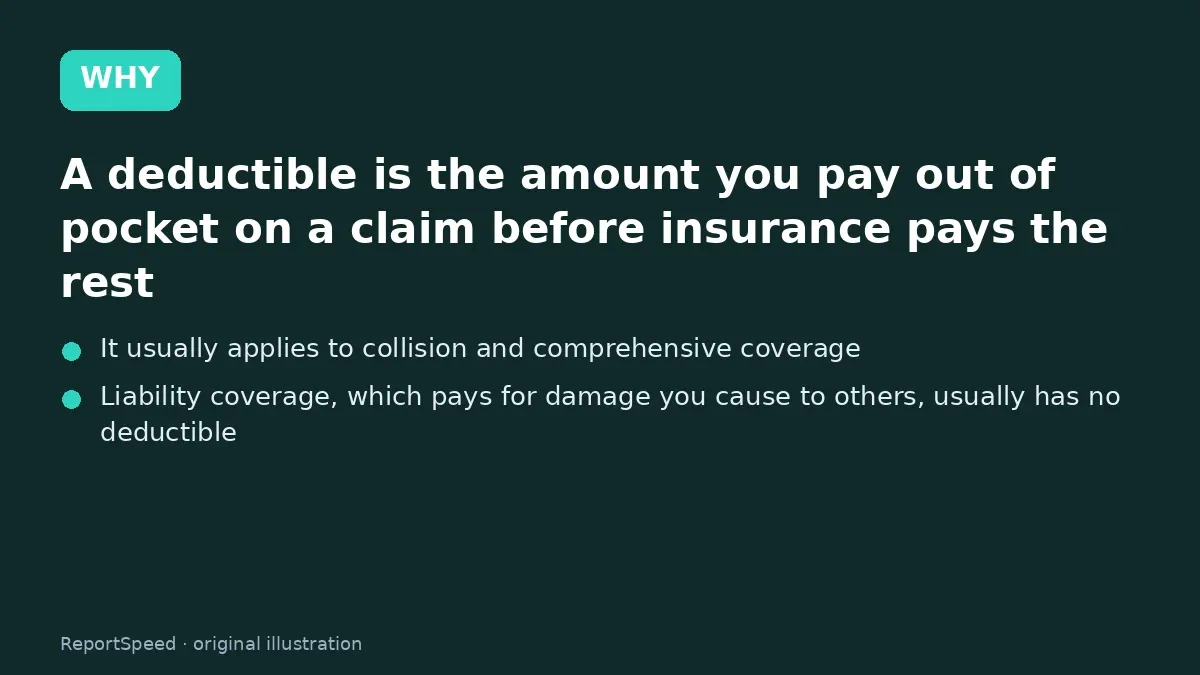
2. Why it happens The cause 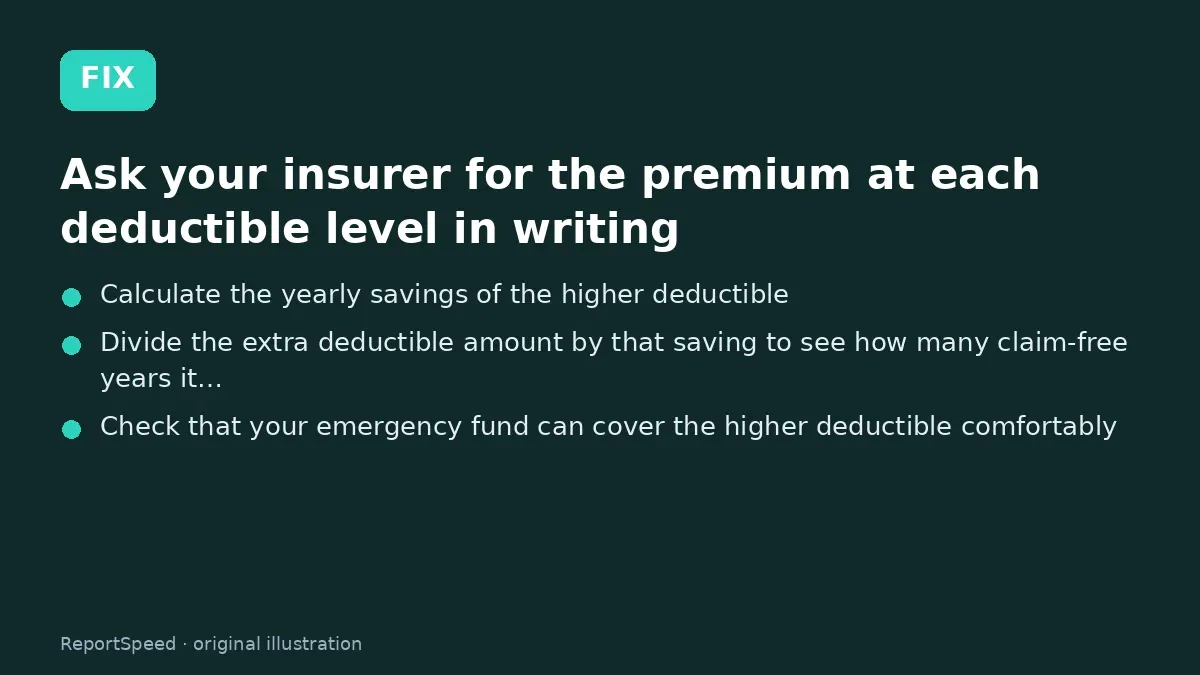
3. The fix The fix 
4. After The result
⚡ Speed Summary
- Pick the highest deductible you can pay without stress.
- Comprehensive and collision can sometimes have different deductibles. A lower comprehensive deductible may cost little and helps with glass, theft or storm damage.
- Picking a $1,000 deductible to save money when you couldn't actually pay $1,000 tomorrow can leave a damaged car unrepaired.

Was this answer helpful?
Tap a star to rate this answer.
Related questions

How far should I sit from the steering wheel airbag?
Keep 10 inches from the air bag cover, tilt the wheel toward your chest, and keep kids 12 and under in the back.
Rate itSolved
Is it safe to drive through a flooded road? How much water can float a car
Never drive into flood water; a foot of rushing water can carry most cars.
Rate itSolved
When can my child stop using a booster seat?
Keep the booster until the seat belt fits across the thighs and chest, and keep kids 12 and under in the back.
Rate itSolved
Does driving faster really waste gas? Speed and fuel economy
Above 50 mph mileage drops quickly, roughly like $0.30 more per gallon for each extra 5 mph.
Rate itSolved
Real experiences
No experiences yet. Be the first to share.