


I'm financing a new SUV with very little down, and the finance manager added GAP insurance for $900 to my loan. He said I need it because the car will be worth less than I owe for a while. Do I need GAP insurance, and is the dealer the only place to get it?
Do I need GAP insurance on a new car loan?
Concerns & risks
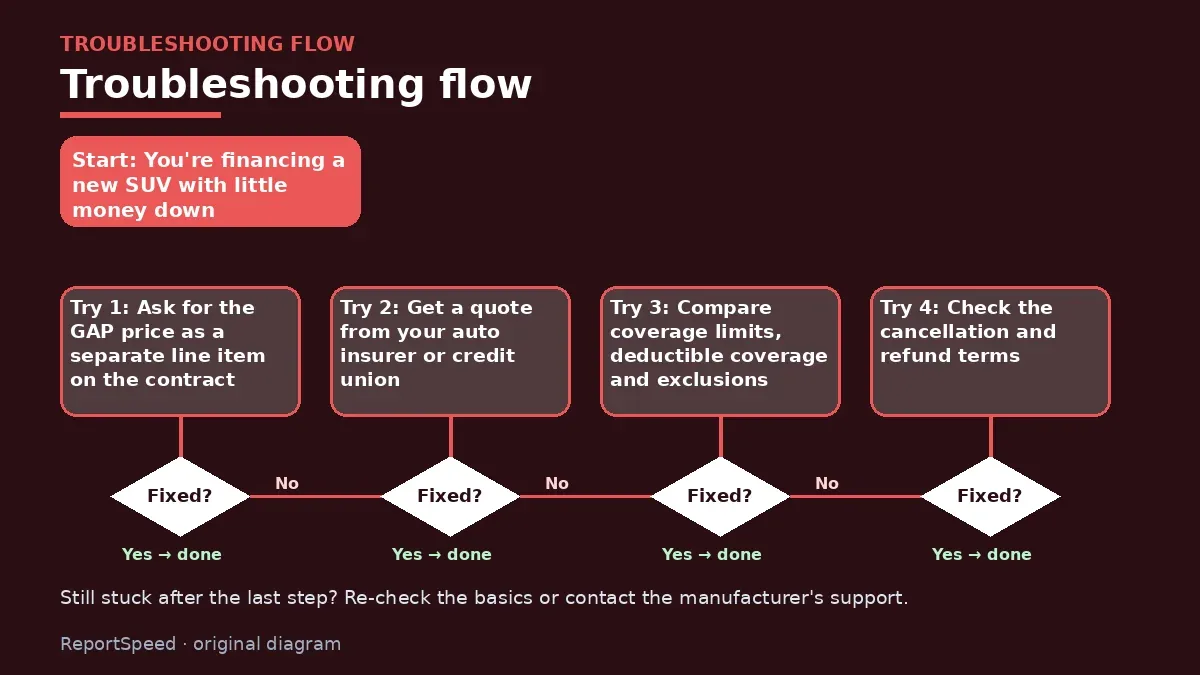
You're financing a new SUV with little money down, and the dealer added GAP coverage into the loan.
| Question | Why |
|---|---|
| What does GAP cost on its own? | Spot inflated pricing |
| Does it cover my deductible? | Coverage varies |
| Is there a payout cap? | Some policies cap payouts |
| Can I cancel for a refund? | You may not need it later |
| Is it required for this loan? | Usually optional |
Causes & evidence
The CFPB explains that GAP (guaranteed asset protection) insurance covers the 'gap' between what you owe on your loan and what your car is worth if it's stolen or totaled and your regular insurer pays only its actual cash value. It's most relevant when you put little or nothing down, have a long loan term or rolled negative equity from a previous car into the new loan. The CFPB also says GAP insurance is optional: a lender or dealer generally can't require you to buy it from them to get the loan, although some lenders may require GAP coverage from a provider of your choice. When it's added to your loan, you pay interest on it too. Auto insurers and credit unions often offer GAP coverage, so compare prices, and check whether you can cancel and get a partial refund once you no longer need it.
Who this applies to: GAP matters most if you financed most of the price, chose a long loan term or rolled over negative equity. If you lease, GAP coverage may already be included, so check your lease. If you paid cash or made a large down payment, you may not need it. Some lenders require GAP but let you buy it anywhere.
Accepting GAP coverage rolled into the loan without comparing prices means paying interest on an add-on you may have bought for less elsewhere.
What to do
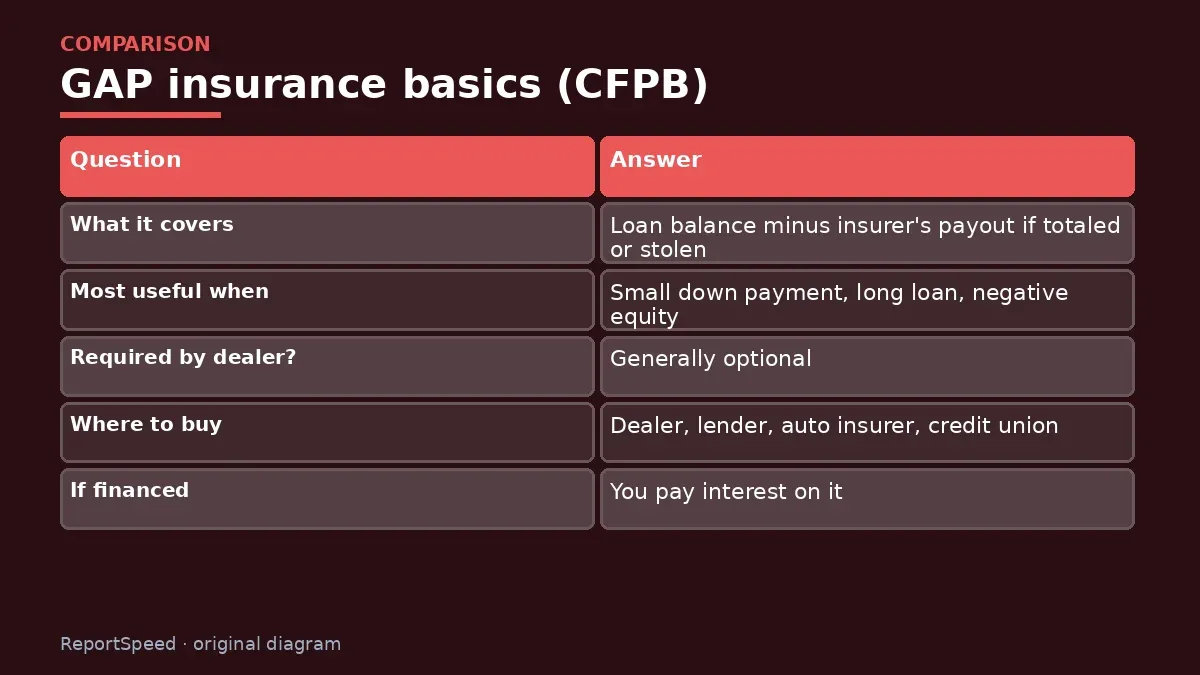
| Question | Answer |
|---|---|
| What it covers | Loan balance minus insurer's payout if totaled or stolen |
| Most useful when | Small down payment, long loan, negative equity |
| Required by dealer? | Generally optional |
| Where to buy | Dealer, lender, auto insurer, credit union |
| If financed | You pay interest on it |
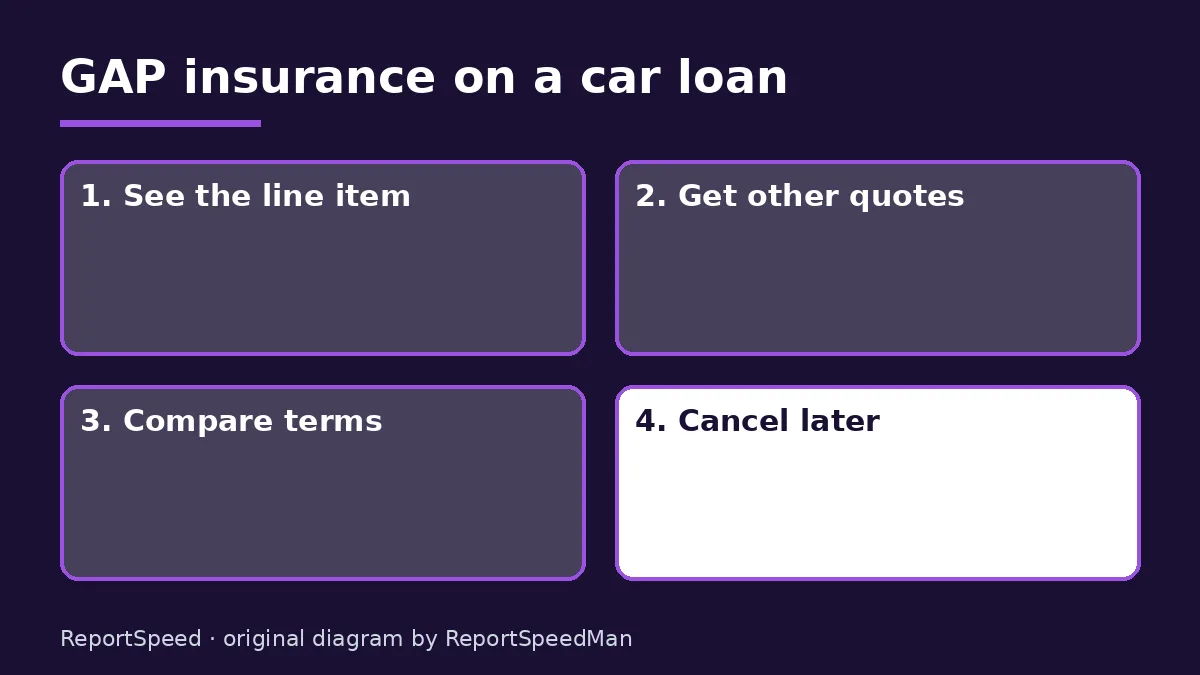
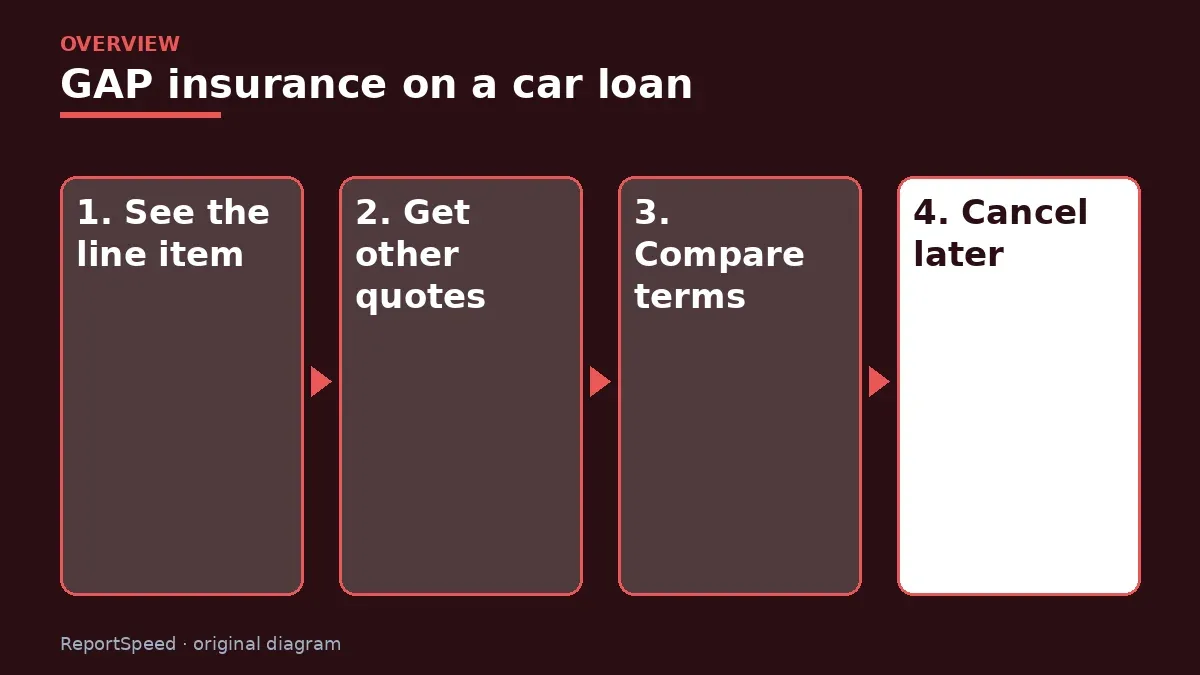
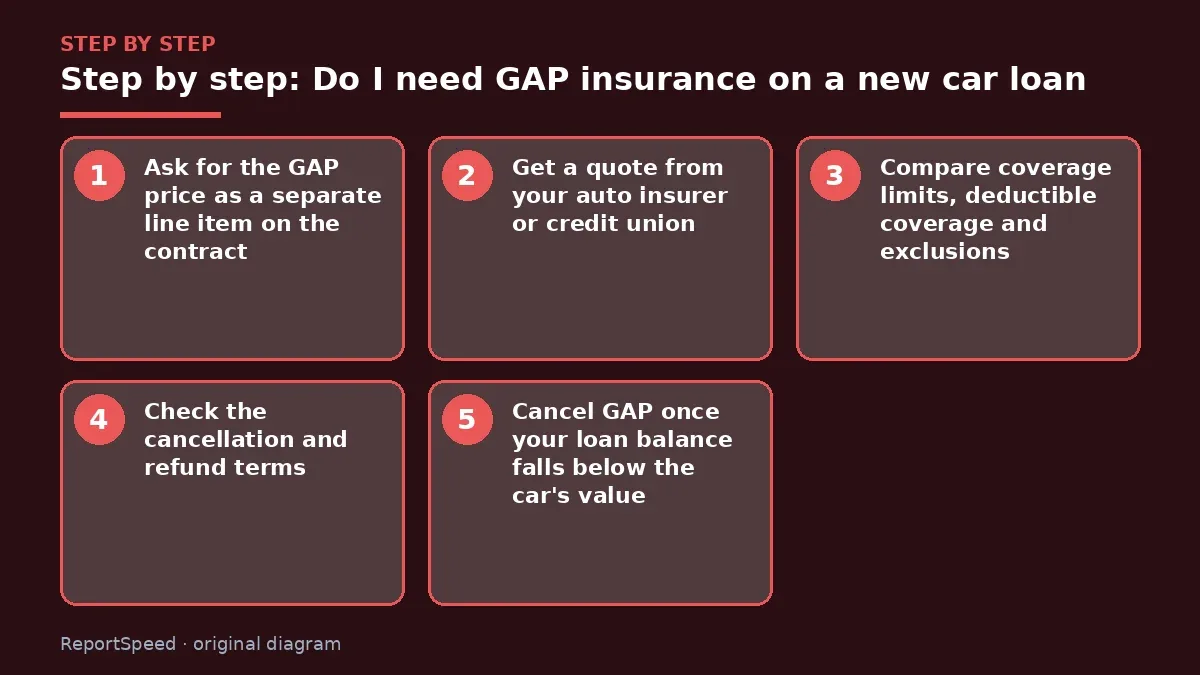
- Ask for the GAP price as a separate line item on the contract.
- Get a quote from your auto insurer or credit union.
- Compare coverage limits, deductible coverage and exclusions.
- Check the cancellation and refund terms.
- Cancel GAP once your loan balance falls below the car's value.
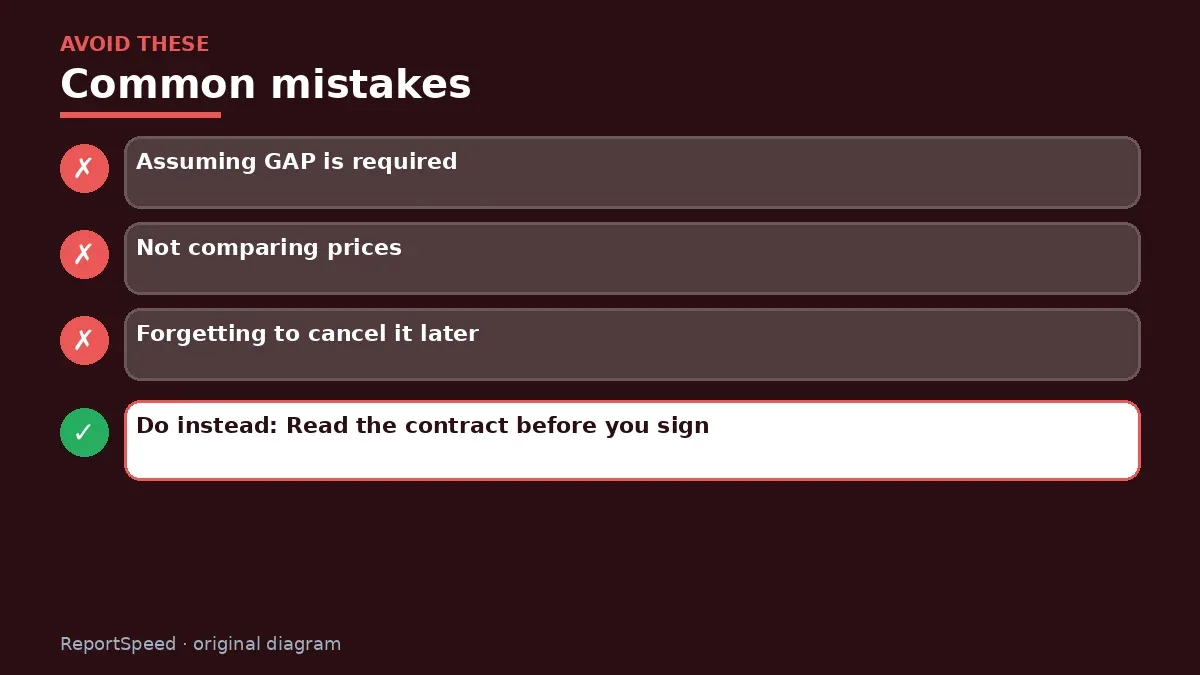
Common mistakes:
- Assuming GAP is required
- Not comparing prices
- Forgetting to cancel it later
ReportSpeedMan tip: Read the contract before you sign: add-ons are sometimes bundled into the monthly payment without being clearly explained.
What I would actually do
I'd ask for GAP as a separate price, get a quote from my insurer the same day, and only take the dealer version if it's competitive and cancellable.
The trade-off people miss: GAP matters most in the first years of a loan with little down. As you pay down the loan, it becomes less useful, so set a reminder to check whether you still need it.
How to tell it worked
You paid a fair price for GAP, or chose not to need it.
Quick FAQ
Can I cancel GAP early?
Often yes, with a partial refund; check the contract.
Does my car insurance include GAP?
Not usually by default; ask your insurer about adding it.
What if I pay off the loan early?
You may be due a refund for unused GAP coverage.
Wrap-up: GAP can make sense with little down or a long loan, but it's optional. Compare the dealer's price with your insurer or credit union, and drop it when you no longer owe more than the car is worth.
Wiki: Credit Card Interest and APR and Compound Interest.
Do I need GAP insurance on a new car loan: official sources I checked
Step-by-step photos
1. Before The problem 
2. Why it happens The cause 
3. The fix The fix 
4. After The result
⚡ Speed Summary
- GAP can make sense with little down or a long loan, but it's optional.
- Read the contract before you sign: add-ons are sometimes bundled into the monthly payment without being clearly explained.
- Accepting GAP coverage rolled into the loan without comparing prices means paying interest on an add-on you may have bought for less elsewhere.

Was this answer helpful?
Tap a star to rate this answer.
Related questions

How far should I sit from the steering wheel airbag?
Keep 10 inches from the air bag cover, tilt the wheel toward your chest, and keep kids 12 and under in the back.
Rate itSolved
Is it safe to drive through a flooded road? How much water can float a car
Never drive into flood water; a foot of rushing water can carry most cars.
Rate itSolved
When can my child stop using a booster seat?
Keep the booster until the seat belt fits across the thighs and chest, and keep kids 12 and under in the back.
Rate itSolved
Does driving faster really waste gas? Speed and fuel economy
Above 50 mph mileage drops quickly, roughly like $0.30 more per gallon for each extra 5 mph.
Rate itSolved
Real experiences
No experiences yet. Be the first to share.