


I'm carrying about $6,000 on a card at a high APR and keep getting offers for 0% balance transfer cards. They all mention a transfer fee and a promo period. Is moving the debt actually worth it once you count the fee, and what are the catches I should look for?
Is a 0% balance transfer card worth the fee?
Concerns & risks
You have a card balance at a high rate, 0% offers keep arriving, and you want to know if the transfer fee and fine print make it worthwhile.
| If… | Then |
|---|---|
| Interest saved over promo > fee | Transfer can make sense |
| You can clear it before promo ends | Best case |
| You'll keep spending on old card | Fix the habit first |
| Payments sometimes late | Set autopay before moving debt |
Causes & evidence
A balance transfer moves debt from one card to another, usually at a low promotional APR for a set number of months. The CFPB notes most transfers come with a fee, typically a percentage of the amount moved, which is added to your new balance. When the promotion ends, any remaining balance starts accruing the card's regular APR. New purchases on the card may not get the promo rate, and a late payment can end the promotion early. Under federal credit card rules, payments above the minimum generally go to the highest-rate balance first, which helps if you do carry mixed balances.
Promo lengths and fees vary by issuer and depend on your credit. Card issuers also set a credit limit for the transfer, which may be lower than your balance.
Moving the debt and then continuing to spend on the old card is how many people end up with two balances instead of one.
What to do

| Item | What to check |
|---|---|
| Transfer fee | Usually a percentage of the amount moved, added to the balance |
| Promo APR length | Number of months at the low rate |
| Rate after promo | The card's regular APR applies to what's left |
| New purchases | May be charged the regular APR |
| Late payment | Can end the promo rate early |
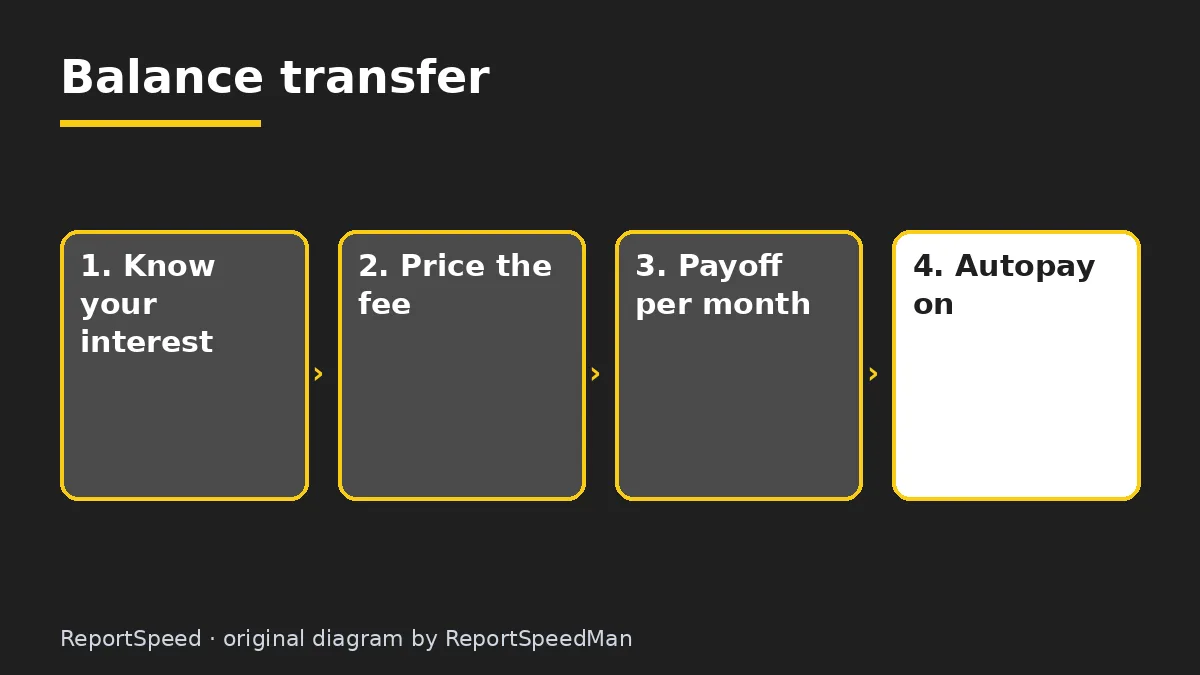
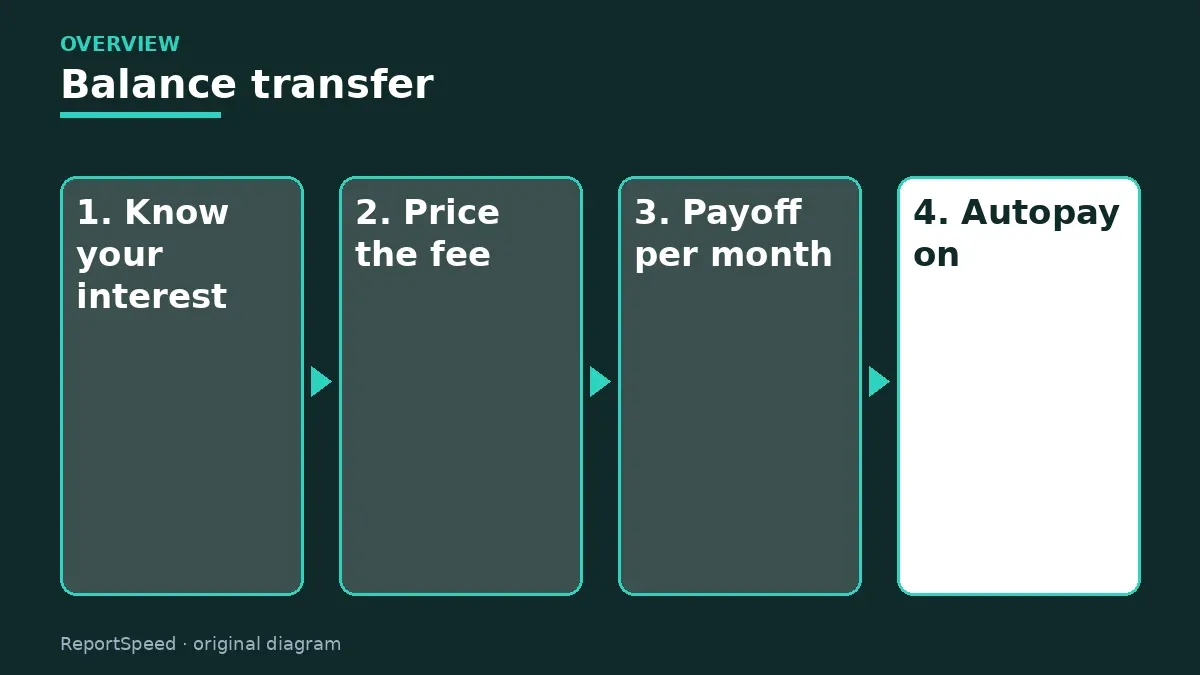
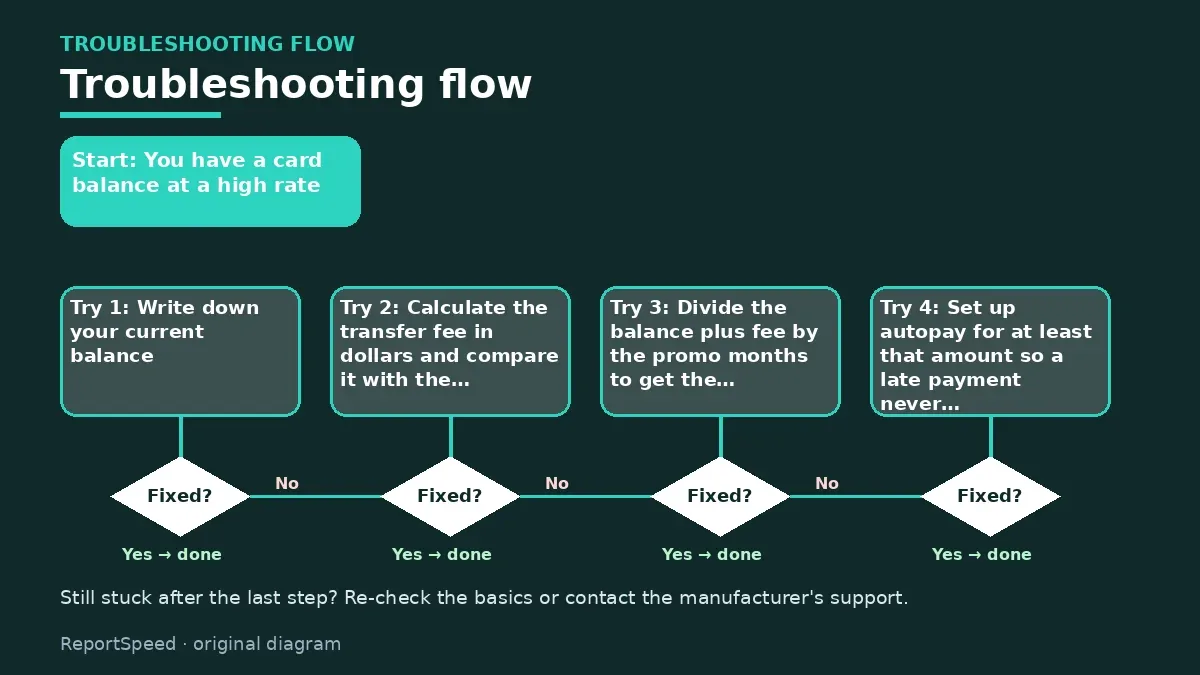
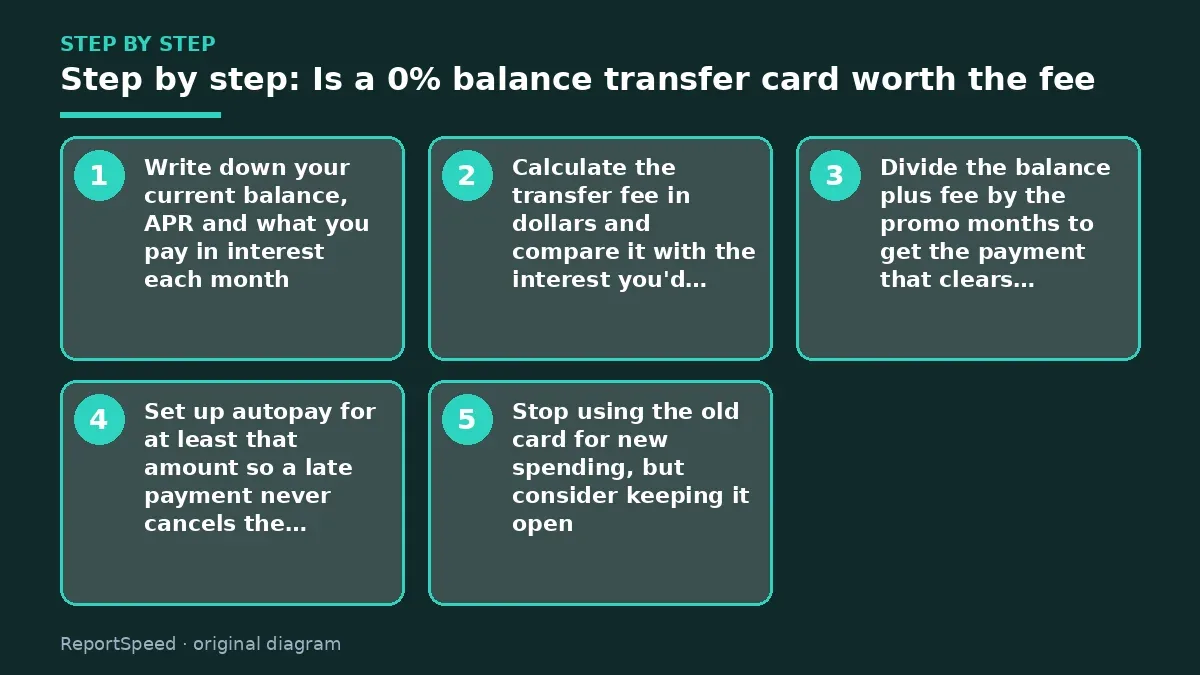
- Write down your current balance, APR and what you pay in interest each month.
- Calculate the transfer fee in dollars and compare it with the interest you'd pay over the promo period.
- Divide the balance plus fee by the promo months to get the payment that clears it in time.
- Set up autopay for at least that amount so a late payment never cancels the promo.
- Stop using the old card for new spending, but consider keeping it open.
Common mistakes:
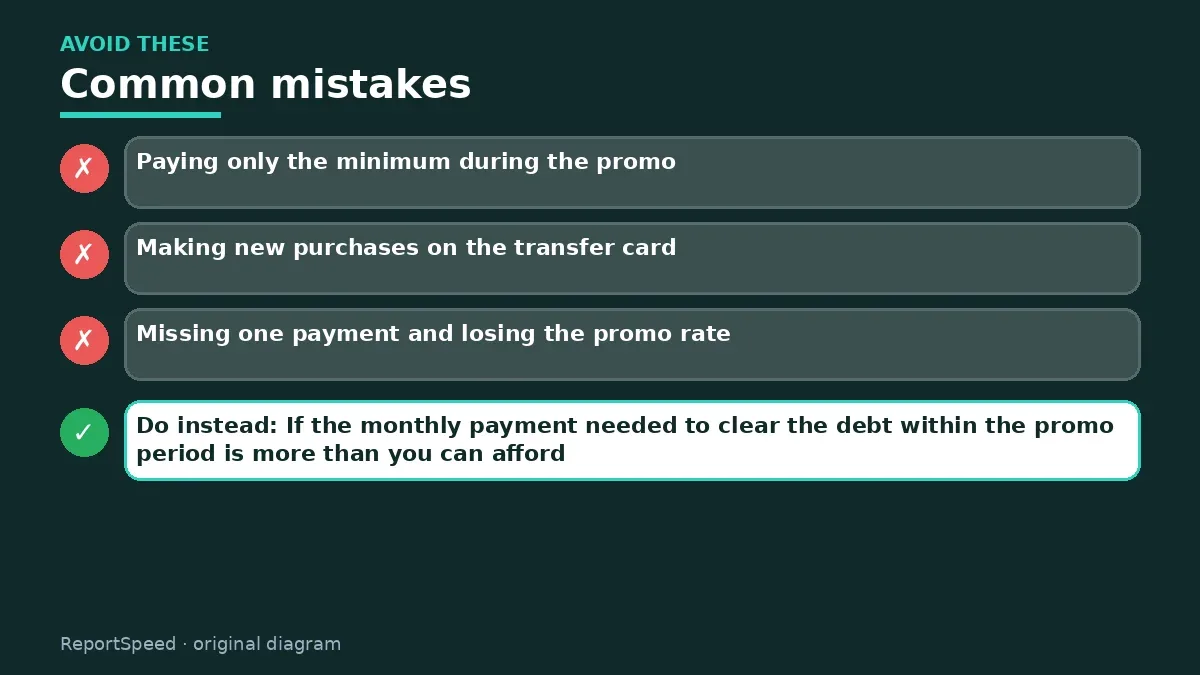
- Paying only the minimum during the promo
- Making new purchases on the transfer card
- Missing one payment and losing the promo rate
ReportSpeedMan tip: If the monthly payment needed to clear the debt within the promo period is more than you can afford, a transfer can still help, but plan for what the leftover balance will cost after.
What I would actually do
I'd work out the dollars before applying: the fee versus the interest I'd pay over the same months, then set autopay to clear the balance a month before the promo ends.
The trade-off people miss: applying for a new card adds a hard inquiry and a new account, which can lower your score for a while. Before a mortgage or car loan, the timing matters.
Proof that it worked
Your balance falls every month and is on track to hit zero before the promo ends.
Quick FAQ
Will it hurt my credit score?
A new card adds a hard inquiry; paying down debt can help over time.
Can I transfer between cards from the same bank?
Usually not.
What if I can't pay it off in time?
The regular APR applies to what's left.
Wrap-up: A balance transfer works when the fee is smaller than the interest you avoid and you have a payoff plan that finishes before the promo ends.
Wiki: Credit Card Interest and APR and Credit Scores and Credit Reports.
Is a 0% balance transfer card worth the fee: primary sources
Step-by-step photos
1. Before The problem 
2. Why it happens The cause 
3. The fix The fix 
4. After The result
⚡ Speed Summary
- A balance transfer works when the fee is smaller than the interest you avoid and you have a payoff plan that finishes before the promo ends.
- If the monthly payment needed to clear the debt within the promo period is more than you can afford, a transfer can still help, but plan for what the leftover balance will cost after.
- Moving the debt and then continuing to spend on the old card is how many people end up with two balances instead of one.

Was this answer helpful?
Tap a star to rate this answer.
Related questions
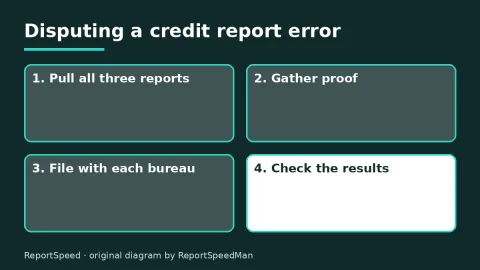
Found an error on my credit report? How to dispute it step by step
Dispute with each bureau and the furnisher, include proof, and expect results in about 30 days.
Rate itSolved
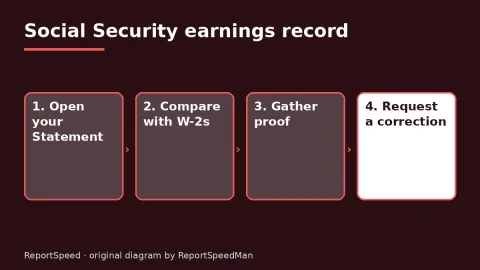
How do I check my Social Security earnings record and fix a mistake?
Check your Statement every year, match it to your W-2s, and correct gaps with proof before the usual window closes.
Rate itSolved
How long should I keep tax records? The IRS 3-, 6- and 7-year rules
Three years covers most returns; six, seven or forever apply in specific cases.
Rate itSolved
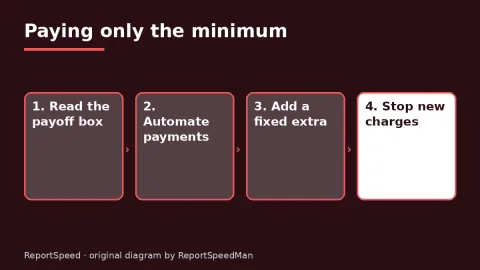
What happens if I only pay the minimum on my credit card?
Minimum payments keep you current but stretch the debt for years.
Rate itSolved
Real experiences
No experiences yet. Be the first to share.