


My car repair came to $480 and payday is still 12 days away. There's a payday lender near work that says I can walk out with cash in 15 minutes. The fee doesn't sound huge. Is a payday loan ever a good idea, and how do I compare it with other options?
Is a payday loan ever a good idea? What it really costs
Concerns & risks
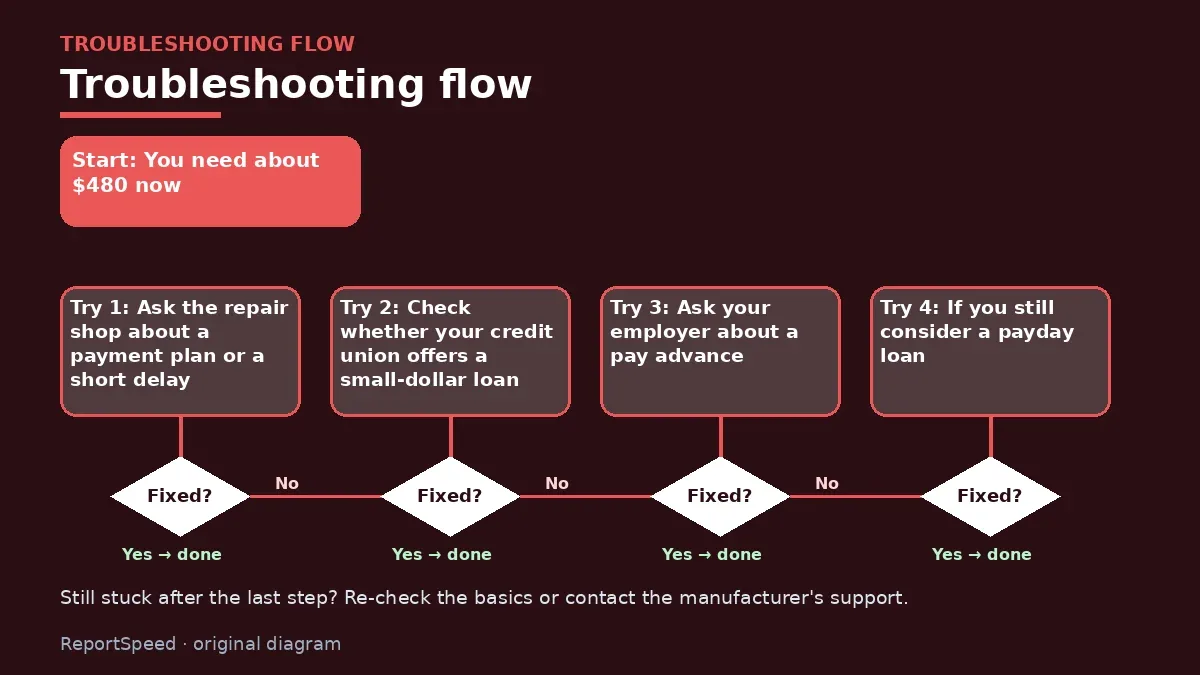
You need about $480 now, payday is almost two weeks away, and a payday lender is offering fast cash.
| Option | What to ask |
|---|---|
| Repair shop | Payment plan or delay |
| Credit union | Small-dollar or payday-alternative loan |
| Employer | Pay advance |
| Utility or landlord | Due-date extension |
| Credit card | Compare APR with the payday quote |

Causes & evidence
The CFPB describes a payday loan as a short-term, high-cost loan, generally for $500 or less, usually due on your next payday. Repayment is often by a post-dated check or permission to debit your account, and lenders generally don't check your ability to repay. Many state laws cap fees at $10 to $30 for every $100 borrowed. The CFPB notes that a typical two-week loan with a $15 per $100 fee works out to an APR of almost 400%, compared with credit card APRs of roughly 12% to 30%. The bigger risk is the rollover: in some states you can pay only the fee and extend the due date, so the fees repeat while the balance stays the same. Rules differ by state, and some states don't allow payday lending.
Who this applies to: payday lending rules are set mostly by states, so whether payday loans are allowed, the maximum fee and rollover limits all depend on where you live. Some states ban payday loans or cap rates low enough that storefront lenders don't operate. Online lenders must follow the law of the state where you live. Active-duty servicemembers and their dependents have extra protection under the Military Lending Act, which caps the rate on many such loans at 36%.
Rolling a payday loan over and paying only the fee is how a two-week loan turns into months of repeated charges.
What to do
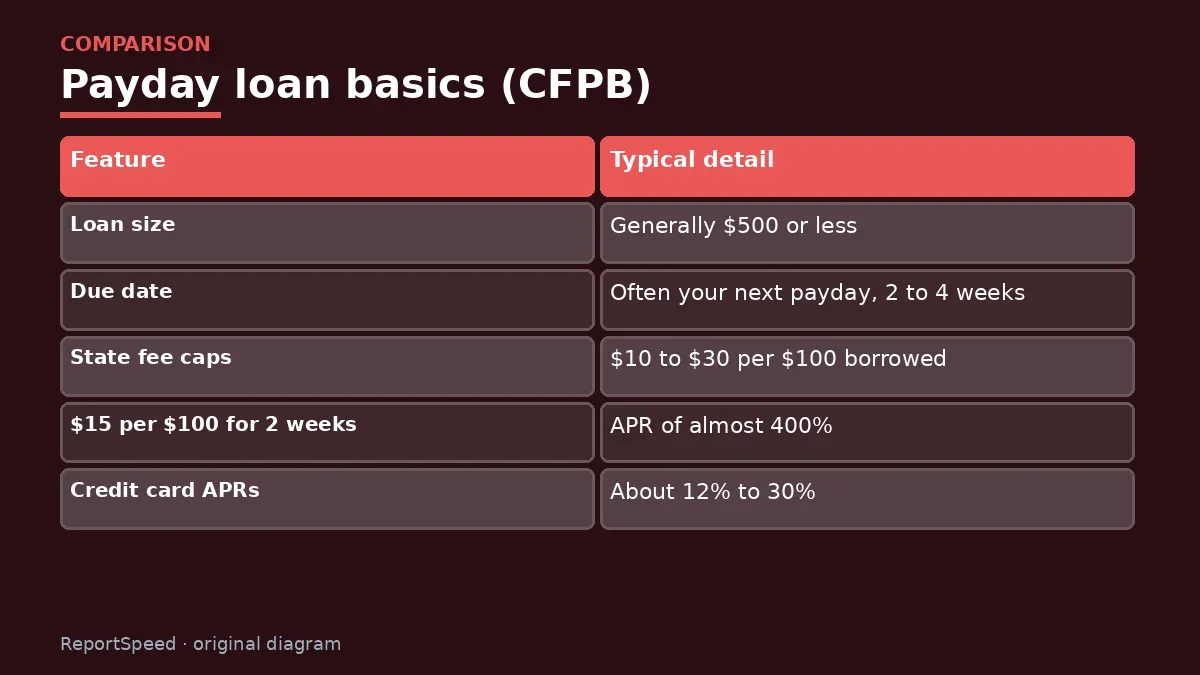
| Feature | Typical detail |
|---|---|
| Loan size | Generally $500 or less |
| Due date | Often your next payday, 2 to 4 weeks |
| State fee caps | $10 to $30 per $100 borrowed |
| $15 per $100 for 2 weeks | APR of almost 400% |
| Credit card APRs | About 12% to 30% |
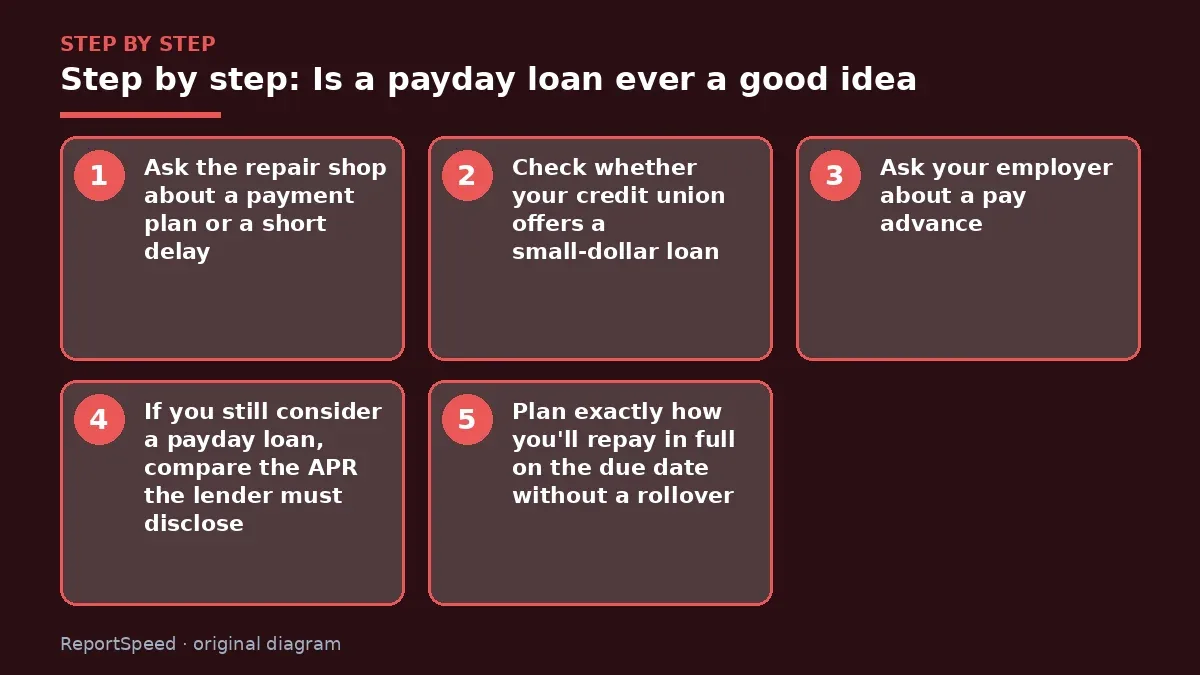
- Ask the repair shop about a payment plan or a short delay.
- Check whether your credit union offers a small-dollar loan.
- Ask your employer about a pay advance.
- If you still consider a payday loan, compare the APR the lender must disclose.
- Plan exactly how you'll repay in full on the due date without a rollover.

Common mistakes:
- Comparing the fee instead of the APR
- Rolling the loan over
- Giving account access without knowing the debit date
ReportSpeedMan tip: Even a credit card cash advance, which is expensive, usually costs less over two weeks than a typical payday loan. Compare the disclosed APRs side by side.
What I would actually do
I'd call my credit union about a small loan and ask the shop for a two-week payment plan before ever walking into a payday lender.
The trade-off people miss: the payday loan's speed is real, but so is the automatic debit on payday. If that debit leaves you short again, you're back where you started plus a fee, and possibly a bank overdraft fee too.
How to tell it worked
Your repair is paid without a payday loan rollover.
Quick FAQ
Does a payday loan help my credit?
Usually not; many lenders don't report on-time payments.
Can I stop the automatic debit?
You can revoke authorization with the lender and tell your bank.
What's a rollover?
Paying a fee to push the due date back, with the full balance still owed.
Wrap-up: A $15 per $100 two-week payday loan is close to 400% APR. Exhaust cheaper options first, and if you do borrow, repay in full and skip rollovers.
Wiki: Credit Card Interest and APR and Emergency Fund.
Is a payday loan ever a good idea: official pages behind this answer
Step-by-step photos
1. Before The problem 
2. Why it happens The cause 
3. The fix The fix 
4. After The result
⚡ Speed Summary
- A $15 per $100 two-week payday loan is close to 400% APR.
- Even a credit card cash advance, which is expensive, usually costs less over two weeks than a typical payday loan. Compare the disclosed APRs side by side.
- Rolling a payday loan over and paying only the fee is how a two-week loan turns into months of repeated charges.

Was this answer helpful?
Tap a star to rate this answer.
Related questions
Found an error on my credit report? How to dispute it step by step
Dispute with each bureau and the furnisher, include proof, and expect results in about 30 days.
Rate itSolved
How do I check my Social Security earnings record and fix a mistake?
Check your Statement every year, match it to your W-2s, and correct gaps with proof before the usual window closes.
Rate itSolved
How long should I keep tax records? The IRS 3-, 6- and 7-year rules
Three years covers most returns; six, seven or forever apply in specific cases.
Rate itSolved
What happens if I only pay the minimum on my credit card?
Minimum payments keep you current but stretch the debt for years.
Rate itSolved
Real experiences
No experiences yet. Be the first to share.