


My bank keeps offering credit monitoring for $15 a month. Do I need it?
Is it worth paying for credit monitoring?
Concerns & risks
You keep seeing ads for credit monitoring services and wonder if it's worth paying for.
Paying for what's free hurts.
Causes & evidence
Free credit reports and freezes cover a lot. See credit score basics and identity theft recovery.
What to do
- Check reports free at AnnualCreditReport.com.
- Use free score tools in your card apps.
- Freeze your credit (free).
- Set up account alerts in your banking apps.
Common mistakes: Common mistakes: paying for something you could do free. You can check free credit reports regularly, set up fraud alerts and freeze your credit at no cost. Some services add insurance or alerts, so read what's included. If you were in a data breach, see if free monitoring is offered. Before buying, check whether your bank or card already includes free score tracking or alerts. Many do. Whatever you choose, nothing replaces reading your reports yourself and acting fast on anything you don't recognize.
Speed Man tip: A free freeze does more to block new accounts than paid monitoring alone.
Wrap-up: Free tools cover most needs. Freeze your credit. Use bank alerts.
⚡ Speed Summary
- Free tools cover most needs.
- Freeze your credit.
- Use bank alerts.

Was this answer helpful?
Tap a star to rate this answer.
Related questions
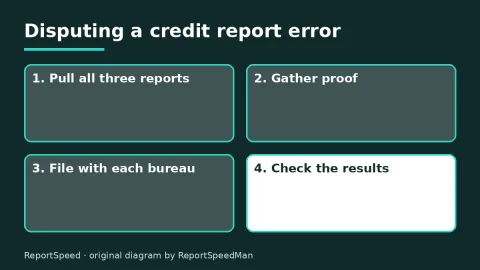
Found an error on my credit report? How to dispute it step by step
Dispute with each bureau and the furnisher, include proof, and expect results in about 30 days.
Rate itSolved
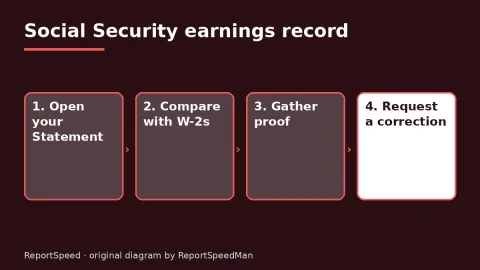
How do I check my Social Security earnings record and fix a mistake?
Check your Statement every year, match it to your W-2s, and correct gaps with proof before the usual window closes.
Rate itSolved
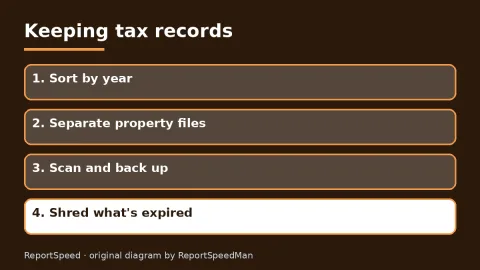
How long should I keep tax records? The IRS 3-, 6- and 7-year rules
Three years covers most returns; six, seven or forever apply in specific cases.
Rate itSolved
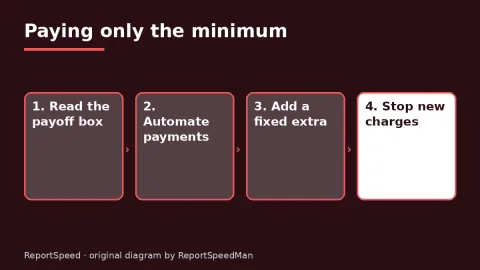
What happens if I only pay the minimum on my credit card?
Minimum payments keep you current but stretch the debt for years.
Rate itSolved
Real experiences
No experiences yet. Be the first to share.